About Us
Accredited investors interested in reviewing the private business plan, structure, and NDA materials are invited to reach out. As with any Opportunity Zone investment, this involves significant risk, is available only to accredited investors, and requires independent review with your own tax and legal advisors. California does not conform to the federal Opportunity Zone tax benefits.
The fire is lit. The water is pure. The community is ready.
What will you add to the pot?
Legal Architecture, Land Heritage & Tax Preservation

Target Audience
Institutional investment committees, estate planning attorneys, CPAs, and high-net-worth land sponsors.

Core Objective
Establish legal rigor and land asset background. Detail how Tract 1897’s historic $350,000 tax basis is shielded from property tax spikes via a Master Ground Lease under California Revenue and Taxation Code § 61(c), while strictly complying with IRS related-party rules under Treas. Reg. § 1.1400Z2(d)-1.

Key Entity Classifications
California LLC: Landowner entity holding fee simple title to 7 parcels (~36+ acres).
Findelaterre LLC: Wyoming LLC holding fee simple title to Lot 23 (~5 acres).
Burney QOZB, LP: Delaware Limited Partnership acting as the operating tenant and owner of depreciable improvements.(to be formed)
Lot 23 Dual Mechanics: Explicitly outline both Commercial/Resort Integration (Findelaterre LLC as co-landlord) and Personal Compound Exclusion (severing Lot 23 to avoid non-qualifying personal use tainting the QOZB).
Land Assembly & Site History
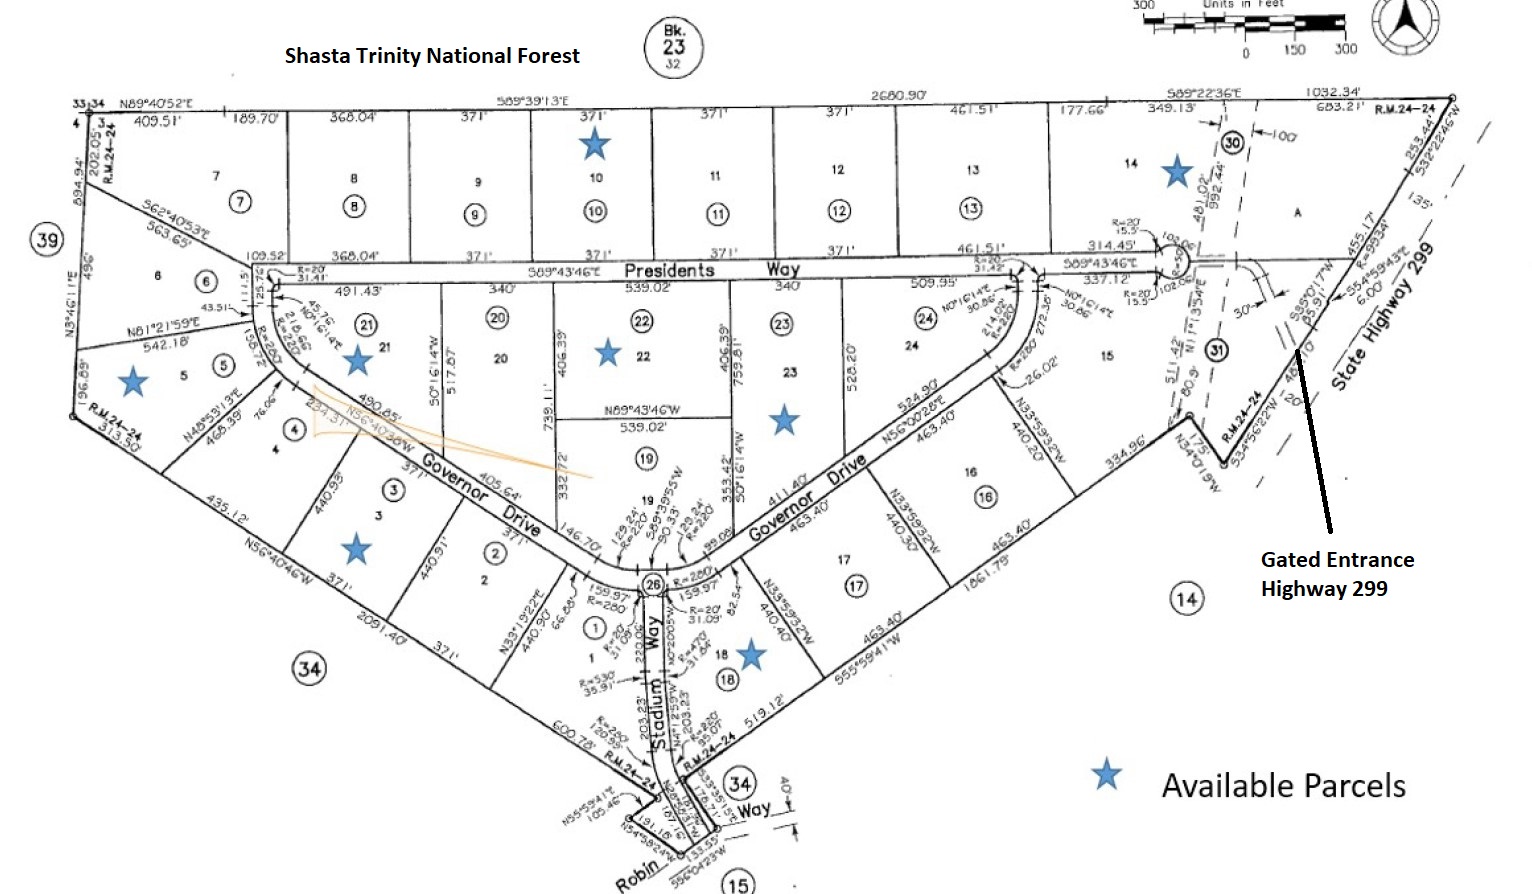
Tract 1897 in Rocky Ledge Estates represents a strategic land assembly in Burney, Shasta County, California. Located beside Burney Falls and Lake Britton, the 41.48 acres comprise eight legally subdivided estate parcels. Originally acquired in 2013 for a historical tax basis of $350,000, the land is currently valued at approximately $3,000,000.
The primary structuring directive for the sponsor team is mobilizing this land for high-yield resort development without triggering a California property tax reassessment or violating Treasury regulations governing related-party real estate transactions.
Master Ground Lease Mechanism
Separate Land and Improvement Estates
To preserve fee title ownership while allowing the Qualified Opportunity Zone Business (QOZB) to construct and own the resort improvements, the land remains owned by the sponsor entity structure
Safe Harbor Covenant
The Master Ground Lease enforces a strict initial term capped under 35 years (e.g., a 30-year initial term with renewal options structured strictly under the 35-year limit). Because fee title never transfers and the lease term remains under 35 years, the historical $350,000 tax basis remains intact, saving the project hundreds of thousands of dollars in annual property tax liabilities compared to a reassessed ~$3,000,000 valuation.
Treasury Related-Party Compliance
Under IRC § 1400Z-2, tangible property purchased from a party with more than 20% common ownership fails to qualify as Qualified Opportunity Zone Business Property (QOZBP). Therefore, deeding land directly to the fund is legally impermissible. However, Treasury Regulation § 1.1400Z2(d)-1 explicitly permits a QOZB to lease property from a related party, provided four mandatory safe harbors are satisfied:
Market-Rate Arm's-Length Rent: Ground rent must reflect fair market value, substantiated by an independent MAI appraisal targeting a 6% to 8% unimproved land yield ($180,000 to $240,000 annually).
Strict 12-Month Rent Prepayment Cap: Pursuant to Treas. Reg. § 1.1400Z2(d)-1, the QOZB is legally prohibited from prepaying ground rent for any period exceeding 12 months.
Zero Substantial Improvement Requirement on Leased Land: While purchased property mandates a 100% basis match in physical improvements, leased tangible property carries zero substantial improvement test under Treasury regulations.
Unsubordinated Fee Title Protection: The fee simple title of California LLC and Findelaterre LLC remains strictly unsubordinated to tenant obligations or leasehold financing. Land ownership cannot be encumbered or foreclosed upon due to tenant-level operational liabilities.
With the legal and tax preservation framework anchored by the master ground lease, review the operational leadership executing the project on the our team page.
Join us in building a successful future with tailored property investment solutions. For inquiries, support, or more information, feel free to reach out.
Quick Links
Resources
Connect With Us
© Rocky Ledge Estates. 2026. All Rights Reserved.